 日本語
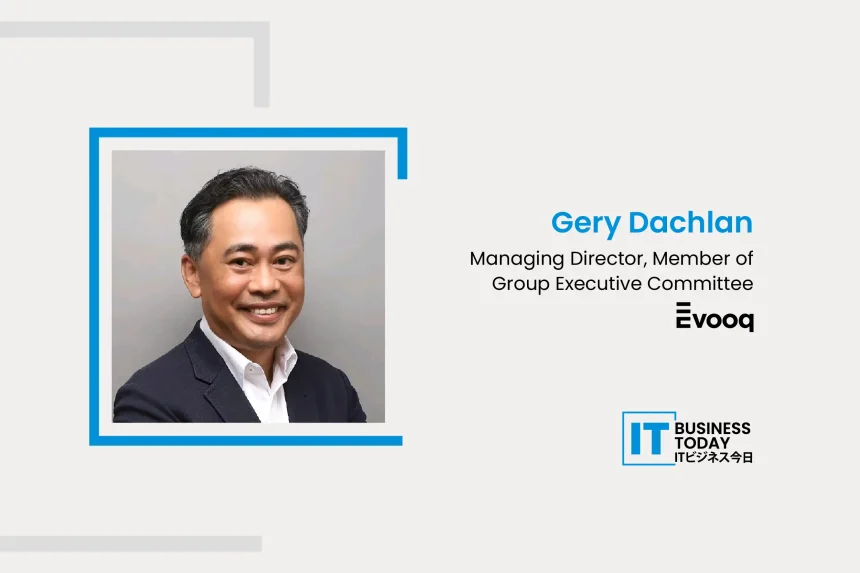
Gery, your career has taken you from corporate banking at Maybank to financial technology leadership at Thomson Financial, Temenos and Avaloq, and now to Evooq. Having witnessed several generations of banking technology, what early experience still shapes how you understand what financial institutions need from technology?
My time in Maybank taught me that from a user’s perspective, introducing technology is not simply a systems project; its in fact a transformation in how people work. A banker focused in understanding clients, making sound decisions and following through on commitments. If a new platform does not help them to do those things better, adoption will be difficult, however sophisticated the technology may be.
People need to understand the rationale for change and just as importantly, what it means for them. Will it remove repetitive tasks, make client information easier to find, or help them prepare for a conversation with greater confidence. When the benefits are clear and relevant to their daily work, people are more likely to embrace a new way of working.
In my experience, successful transformations start by involving users early and designing around the realities of their roles. It requires training and continuous support as people adjust, because positive change can be disruptive at first. The measure of success is not simply that a system has gone live, but that people are using it confidently and it is making their work and life easier and more effective.
You have spent much of your career working with private banks and wealth management institutions across different markets. Capgemini’s 2026 World Wealth Report found that only 17% of high-net-worth individuals consider their advisory experience seamless and personalised. What needs to change for wealth managers to close this gap?
In my experience, most banks still struggle to be able to view a client holistically, i.e. bringing together their objectives, risk tolerance, holdings and relevant circumstances, and making that information useful to the adviser at the point of conversation.
Too often, information sits in different systems, so the client has to repeat themselves and the adviser spends valuable time assembling a picture that should already be available. A more connected workflow can help an adviser prepare for a meeting, see how a proposed investment affects the wider portfolio and follow up consistently afterwards. Most clients want to know the impact to their investment portfolio given their different market conditions – a good adviser should have the capability to support the client with this.
Offering more products or sharing more market information doesn’t make the experience personal. The client has to feel that you understand what matters to them and why a recommendation fits their plan. Technology allows the adviser to do their best work, but the adviser still needs to listen, ask the right questions and exercise judgement.
Evooq’s philosophy centres on making complex things feel simple across portfolios, risk and structured products. Having worked with sophisticated financial systems throughout your career, what does it take to simplify complexity without losing the depth and precision that financial institutions depend on?
Simplicity starts with understanding the decision a person needs to make. An adviser discussing a portfolio with a client needs a clear view of the important risks and trade-offs. A risk specialist may need to go much deeper into the assumptions, calculations and underlying data. Both should be working from the same numbers, but their respective screens should reflect their needs.
For a structured product, for example, an attractive coupon should be presented alongside the conditions for receiving it, potential losses, issuer exposure and the consequences of selling early. The user should also be able to drill down when a number get questioned or challenged. A clean interface alone does not create simplicity, it also requires work around data quality and modelling underneath. The real test is whether the adviser can explain the limitations and provide options to his client to be able to act with confidence.
Despite years of digital transformation, many wealth management operations still rely on disconnected systems and fragmented workflows. From your experience across the industry, what has made integration so difficult, and what becomes possible when wealth management technology operates as a connected ecosystem?
Banks do not set out to create fragmented systems. Their technology has evolved over decades, often through acquisitions, product launches and responses to changing regulation. Different teams have made sensible decisions at different times, but the result can be multiple records of the same client, inconsistent product data and manual hand-offs between systems.
Integration is therefore about more than connecting interfaces. Institutions need agreement on which data is trusted, who owns it, how it is kept current and how information can be used securely across markets. They also have to make change without interrupting a business that clients rely on every day.
A connected ecosystem allows a recommendation to follow a coherent path: from understanding the client and analysing the portfolio, through suitability checks and adviser review, to execution and ongoing monitoring. It does not require every bank to replace its core system which by itself can be a massive undertaking. The primary focus should be to give people the full picture when they need it should be and to connect what already works well.
AI is creating new possibilities for investment advisory, but private banking has always depended on trust, relationships and human judgement. As AI becomes part of everyday wealth management workflows, where do you see the greatest opportunity to make advisors more effective, and what should remain distinctly human?
The quickest win from AI is time and efficiency. AI can pull together what an adviser needs before a meeting, summarise research reports, spot a change in a client’s portfolio and draft a first proposal. That frees the adviser up for the conversation itself, which is where the value is.
However, an AI-generated answer is only as good as the data and controls behind it. Banks need to know which sources it is using, whether the data is current and who is accountable for checking the output. Banks must also protect client information and test for errors or product bias. The riskier the task, the tighter the oversight should be.
What remains human is the responsibility to understand the client, weighing the trade-offs and have an honest conversation, especially when circumstances are uncertain or the advice isn’t what the client wants to hear. The biggest asset of any bank and its adviser is trust, and clients trust an adviser who can explain a decision and stand behind it, not simply when a system produces an answer quickly.
Through Edgelab, Evooq brings advanced risk analytics into the broader wealth management environment. As portfolios become more diverse across asset classes, markets and investment products, how can technology help wealth managers move beyond assessing individual holdings to understanding risk across the entire portfolio?
A holding can look reasonable on its own and still add to a concentration the client already has. Consider an investor who owns shares in a company, a fund that also holds those shares, and a structured product linked to the same company. Looking only at product labels or asset-class allocations may not reveal how much depends on the same underlying exposure.
Technology can bring those positions together, where the necessary holdings and product data are available, and show how the whole portfolio would react to moves in markets, interest rates or currencies. For structured products with conditional or non-linear payoffs, it is important to model their actual terms rather than treat them as ordinary shares or bonds. An adviser can then compare the existing portfolio with the effect of a proposed investment and perform risk modelling. Risk analytics also banks to provide more structured advice across all its advisers and not just based on a general recommendation list from its investment team.
That said, models are decision-support tools, not guarantees. Correlations can change, private-asset valuations can go stale and some holdings may not always be visible. Good analytics should make those limitations clear, so the discussion is informed rather than falsely precise.
Hong Kong’s latest SFC-HKMA survey recorded HK$3.9 trillion in structured product transaction value during 2025, a 53% year-on-year increase. As structured products gain importance across Asian wealth markets, where can technology make the biggest difference in improving transparency, evaluation and portfolio suitability?
A 53% jump shows how strong demand is. It also means much more money is going into products that are harder to understand than they look, so transparency has to keep pace.
Before anyone invests, they should see how the product pays out in different scenarios, and the key terms should be easy to compare: the underlyings, coupon conditions, barriers, maturity, issuer credit risk and what happens if they need to sell early. Costs and pricing should be clear too, where that information is available. A high headline coupon tells you very little on its own.
Then there is suitability. A product may match a client’s risk profile on paper but could also increase an existing exposure to the same underlying assets, issuer or currency. Advisers need to see that before making a recommendation and be able to explain the trade-offs to the client.
Finally, the work does not end at the point of sale. Monitoring key events and documenting decisions can help advisers have timely conversations throughout the product’s life. The objective is not to make every product look simple; it is to make its complexity visible and manageable.
You now lead Evooq’s business across Asia Pacific and the Middle East, two regions with very different wealth management ecosystems. What differences have stood out in how financial institutions approach technology adoption, and how do you build a regional strategy that accounts for these distinct market realities?
The first thing I would say is that neither region is a single market. Each country in Asia-pacific have different regulatory frameworks and business models. The same is true across the Middle East. Within each market, an international private bank, a domestic bank and an independent wealth manager may have very different priorities.
Wealth management market in Singapore and Hong Kong is relatively mature and conversations may focus on improving advisory workflows. At Maybank, for example, we are working together on AI-supported tools that bring portfolio insights and risk analytics into the relationship manager’s workflow. In the emerging markets and in the Middle East, banks are assessing where they should proritise technology investments to bridge the gap between existing systems and modern, scalable client experiences.
Rather that adopting a one-size-fits all strategy, our approach is calibrated to the needs of each bank for its own market. Evooq’s solution set is modular which gives us a high degree of flexibility to configure a solution that best satisfy our clients’ needs with a quicker time to market.
Having spent years on the commercial side of banking technology, you’ve seen how financial institutions evaluate and adopt new platforms. Beyond product capabilities and technical performance, what ultimately earns a technology provider the confidence of a bank, particularly when the relationship is expected to last for years?
As it is with our clients in private banking, trust is earned by being honest about what you can deliver and then doing what you say you will do. Banks need to know that a provider understands their business, will be transparent about limitations and can work constructively with their teams when challenges arise.
I strongly believe in client centricity, and a trusted partner should support a bank during implementation and after the system goes live. That means taking operational resilience and data governance seriously but also being clear about practical questions: who owns a problem, how changes are managed, how the bank can access its data. A bank should not have to rely on promises that cannot be tested.
The best partnerships also have shared measures of success. Is the solution being used? Are advisers spending less time on avoidable administration? Are decisions easier to explain and controls easier to evidence? Those outcomes matter more than simply delivering a project on schedule.
You have witnessed the evolution of financial technology across several decades, and now lead a business operating at the intersection of AI, investment intelligence and connected wealth platforms. What do you believe will fundamentally change about wealth management over the next five years, and which industry assumption do you think deserves to be challenged?
Also Read: Interview With Matthew Edward Loh, Co-founder and Chief Executive Officer @ Bioark
I believe advice will become more continuous and more portfolio-centred. Instead of waiting for the next scheduled review, advisers will have better tools to recognise when a meaningful change in a client’s circumstances or portfolio calls for a conversation. With the right controls, AI and better-connected data can help them prepare for that conversation and explain the implications more clearly.
Over the next few years, I also personally believe that it is becoming increasingly likely that most people will use AI agents as autonomous representative to negotiate and transact with banks. You can already see early tools such as Meta’s Muse, OpenAI’s dots and Claude’s Duet already navigating banking interfaces on users’ behalf. At this juncture, there is still widespread pushback from the banks allowing third-party agents connecting to their agents or banking systems, and widespread adoption will hinge on resolving security, liability and regulatory concerns. In that scenario, the role of the adviser may be narrowed on more complex, or cross disciplinary advice such as estate planning.
That outcome is not guaranteed. There will still be clients that want a human connection and prefer an adviser to whom they can call and rely on. The winners in the industry will not ultimately be those that automate the most interactions; they will be those that make expertise more accessible while preserving accountability and trust.
 English